Is a VA Loan Always the Best Choice for Veterans?
 Pearl Cook
When It Is — and When It’s Not
If you’re a veteran or active-duty service member, you’ve probably heard this before:
👉 “You should always use your VA loan.”
And look… I get where that comes from. VA loans are one of the best benefits out there.
But I’m going to say something you don’t hear often:
👉 A VA loan is not always the best choice.
And honestly, that’s a good thing to understand—because it means you’re making decisions based on strategy, not just assumption.
Let’s walk through when using your VA loan makes the most sense… and when it might not—especially if you’re PCSing or buying in a market like San Antonio.
First, Let’s Be Clear: VA Loans Are Powerful
Before we get into the “when not to,” let’s talk about why VA loans are so strong.
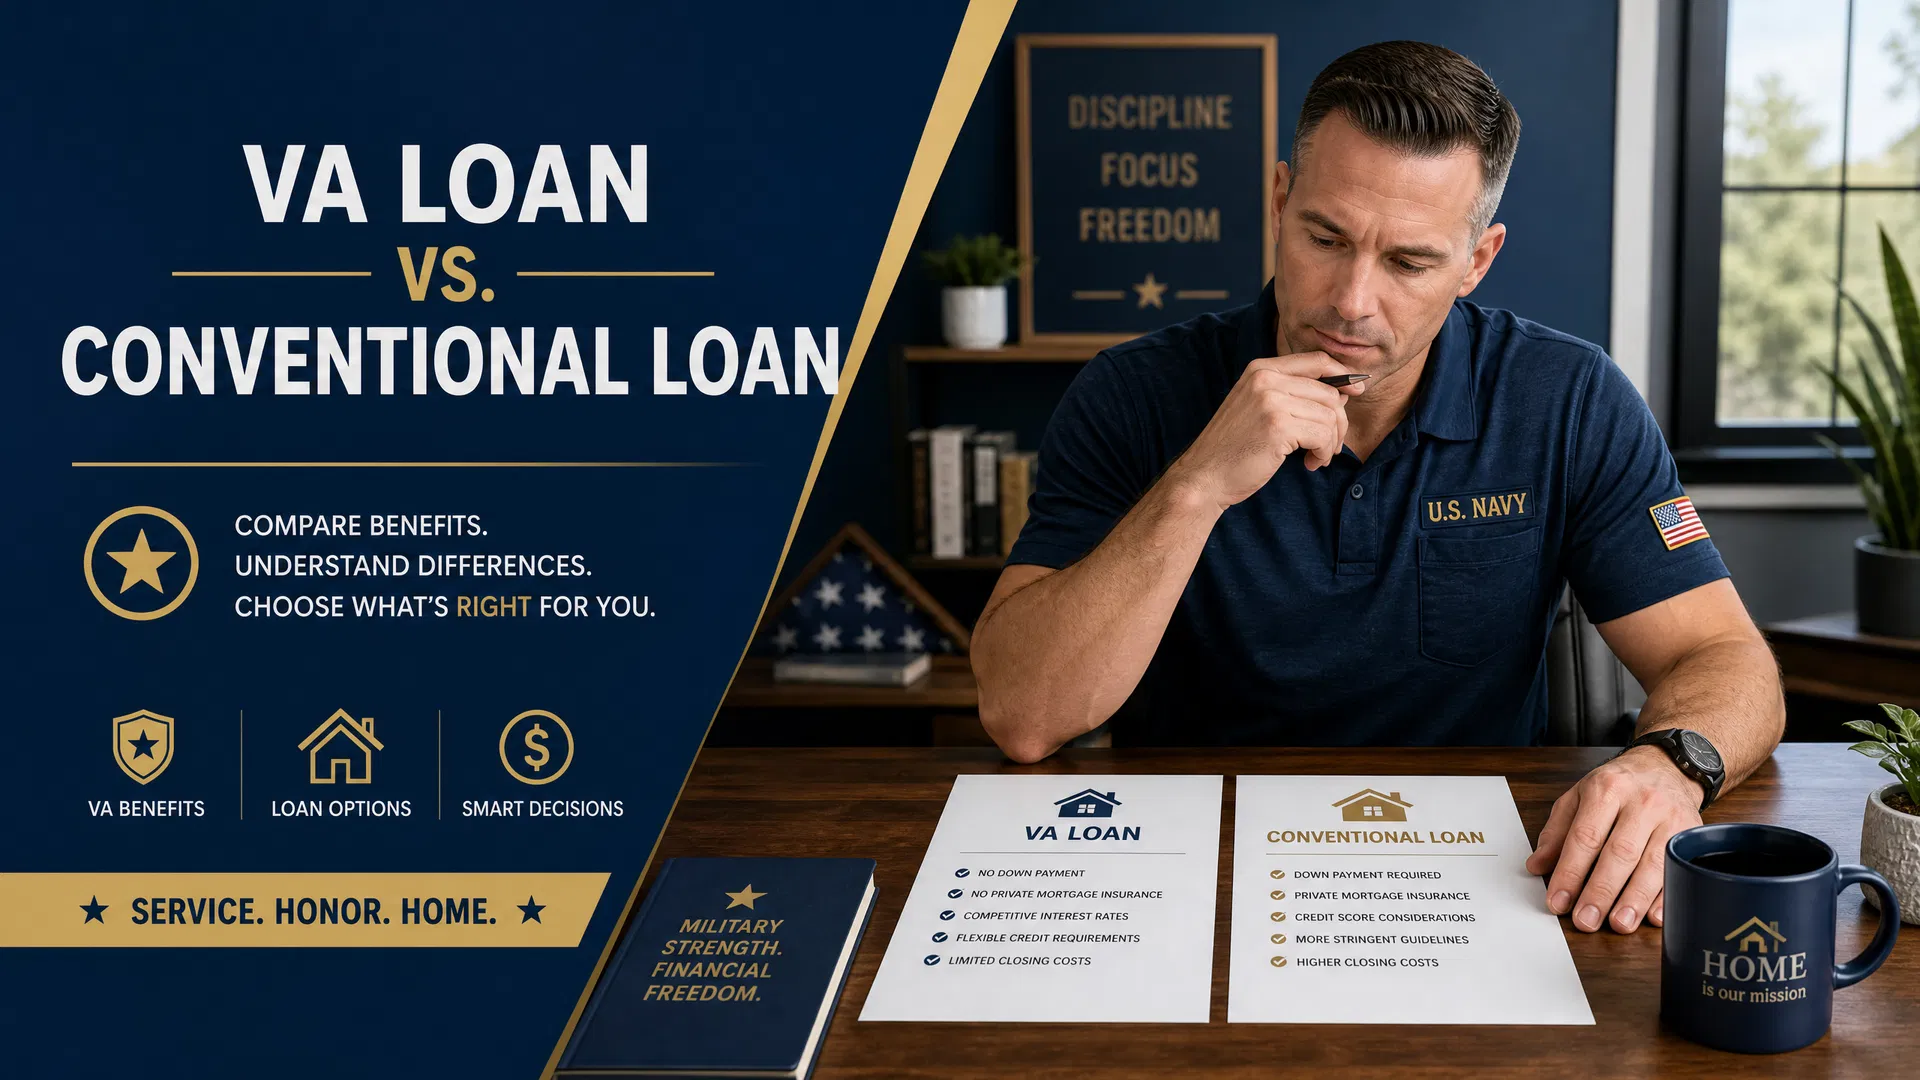
VA loans offer:
- No down payment in most cases
- No monthly mortgage insurance
- Flexible credit guidelines
- Competitive interest rates
For many veterans, this is the easiest and most affordable way to get into a home—especially in areas like San Antonio where many military families relocate and settle long-term.
But just because something is powerful doesn’t mean it’s always the right move.
When a VA Loan Is the Best Choice
Let’s start with where VA loans really shine.
You Want to Keep Cash in Your Pocket
If you don’t want to drain your savings for a down payment, VA loans are hard to beat.
This is especially helpful if:
- You’re PCSing into San Antonio or relocating on orders
- You have moving expenses
- You want reserves after closing
👉 Zero down doesn’t mean less buying power—it means flexibility.
Your Credit Isn’t Perfect
VA loans tend to be more forgiving than conventional loans when it comes to credit.
If your score isn’t where you want it to be yet, VA may open doors that other loan types won’t—something I see often with buyers moving into the San Antonio area who are trying to get settled quickly.
You’re Buying a Primary Residence
VA loans are designed for homes you plan to live in.
If this is your primary home, especially for the next few years, VA is often the strongest option—whether you’re planting roots in San Antonio or just arriving on a new assignment.
You Want a Lower Monthly Payment
Because there’s no mortgage insurance, VA loans often come with lower monthly payments compared to low-down-payment conventional loans.
That can make a big difference long-term, especially if you’re trying to stay comfortable during a PCS transition or adjusting to a new cost of living.
When a VA Loan Might Not Be the Best Choice
Now let’s talk about the part most people don’t bring up.
There are situations where using your VA loan might not be the best move—or at least not the only option you should be looking at.
You’re Not Planning to Live in the Home
VA loans are designed for primary residences.
That means you need to intend to live in the home, typically within a reasonable timeframe after closing.
So if your plan is:
- To buy a rental property right away
- To invest without ever living in the home
- Or to purchase purely for income
👉 A VA loan is not going to be the right fit here.
Now, could you buy a home in San Antonio with a VA loan and turn it into a rental later? Yes. That’s actually a strategy many military families use when they PCS again.
But going into it with the intention not to live there from the start is where it doesn’t align with VA guidelines… and it’s considered to be fraud.
You’re Buying With Someone Who Is Not a Veteran
This one comes up more than you’d think.
If you’re buying with someone who is not your spouse and not a veteran, things can get a little more complex.
Depending on how the loan is structured:
- Only your portion of the loan is backed by the VA
- A down payment may be required
- You may not be able to use full VA financing
👉 In some cases, a conventional loan or FHA loan may actually be simpler and cleaner and require a lower down payment.
This doesn’t mean VA is off the table—it just means we need to look at both options and structure it the right way.
You’re Putting a Large Down Payment Down (But Let’s Talk Strategy)
You’ll hear this a lot:
👉 “If you’re putting 20% down, just go conventional.”
And sometimes that’s true… but it’s not that simple.
Here’s what we actually look at:
- How do the interest rates compare?
VA rates are often still more competitive. - Is there a VA funding fee?
Are you exempt? Are you financing it? Paying it out of pocket? - How much VA entitlement do you have available?
Do you want to preserve it for another purchase—especially if you plan to PCS again? - How long are you planning to stay in the home?
Short-term vs long-term changes the strategy completely. - How quickly do you want to close?
Sometimes a conventional loan will offer an appraisal waiver, allowing you to close quicker and without concerns of an appraisal coming in low.
👉 So instead of defaulting to conventional, we compare both side by side.
Because sometimes:
- VA still wins even with money down
- And sometimes conventional makes more sense
But you won’t know unless we actually run the numbers.
The Real Takeaway
This is why I always say:
👉 It’s not about which loan is “better” — it’s about which loan is better for you.
There’s no one-size-fits-all answer.
The right move depends on your goals, your timeline, and how you want this home to fit into your bigger financial picture—especially if you’re navigating a PCS or planning your next move in or out of San Antonio.
No pressure. Just guidance when you’re ready.
— Pearl